There is a lot of potential in Continental Europe

Sompo has declared Europe to be one of its growth markets. You have hired a significant number of people here in recent years. Now prices in the industrial insurance market are declining. How much does that affect your growth strategy?

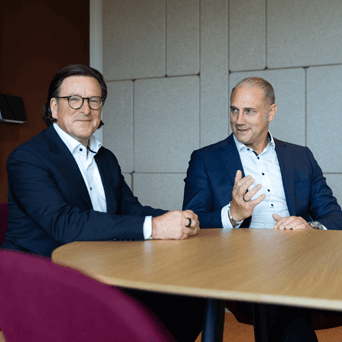
Brand: In Continental Europe, we are on a clear growth path. This path is very long-term in nature and therefore more independent of market conditions. Naturally, we repeatedly have to deal with both hard and soft market phases. For us, the focus is not just on pure growth, but on building a sustainable and profitable business. 

In this regard, local empowerment—that is, granting extensive authority to our local units—along with top-notch technical expertise and the necessary discipline in the underwriting process, play a central role.  

To what extent are the changed market conditions disrupting your plans? 

Expert insight

We are convinced that even during softer market phases, we have ample opportunity to underwrite profitable business and achieve sustainable growth.

Ralph Brand

President, Insurance, Continental Europe & Turkey

How are your long-term growth plans defined? Do you have guidelines or specific goals for the next three or five years?  

Brand: Of course, like any other company, we draw up our annual plans as well as further plans for the coming years. When we started here three and a half years ago, we set our goal of being regarded as a leading insurer in commercial and industrial insurance. As an initial target, we set ourselves EUR 1 billion in premium volume, though not as a fixed plan, because the market can of course change and because we want growth to be profitable. 

And where do you currently stand on the way to EUR 1 billion in premium? 

Brand: By the end of this year, we will be about halfway there. For us, after three and a half years, that is an extraordinary result, one we are very pleased with. During this period, we have also hired more than 300 new colleagues across Continental Europe and have been able to win more than 2,700 new client relationships in large-corporate business in Europe alone. 

Could the second half, in other words doubling the half-billion achieved so far, now become significantly tougher? 

Brand: As I said, together with the country organizations, and also based on input from them, we develop plans that are ambitious but realistic. If market developments lead to us not growing as quickly in one area as we had intended, then we will not do so. I cannot tell you today that we will need exactly another three years for the second half-billion. The time frames are too long and market movements too fast for that. 

Where do you want the journey to go after that? 

Brand: We do not intend to stop at the first billion; it is a first milestone. There is still considerable potential in Continental Europe, including through up-selling and cross-selling. 

What does the situation currently look like for you in Germany? 

Expert insight

A key strategic priority is strengthening our team. We’re already thinking about what our needs might be in the coming years. This isn’t just about market-facing roles in underwriting or sales – it’s about building an industrial insurer. That means we’re also investing heavily in finance, claims, and operations.

Malte Dittmann

Country Manager, Insurance, Germany & Austria

We need to match our growth with the appropriate organizational structure. That may not be glamorous, but it’s important because, given our strong customer focus, it makes us less dependent on market cycles. Industrial customers remain highly demanding, yet they also appreciate it when they get what they expect.  

And what do they expect? 

Dittmann: Things that are basically fundamental virtues for us: service, that the client receives English wording, that their questions are answered, and that they receive a proper policy within a reasonable timeframe. 

How difficult is it for you to find employees? 

Dittmann: We’re currently finding it much easier to recruit new employees than we were two years ago. I can’t say for sure whether this is a general market trend or due to the growing recognition of the Sompo brand. But we’re noticing that the response to job postings is higher and of better quality.  

What do you look for in particular when recruiting employees?  

We need innovators; we need people who are eager to take on responsibility and who are also willing to face that responsibility. In the world we operate in, much of what we do is tailor-made. That’s probably why we need a few more hands on deck. We want to act as a leading insurer and work with our customers to develop solutions. 

You say that the competition for skilled professionals, which we have spoken a lot about in recent years, has weakened. Is that because others are hardly hiring anymore? 

Dittmann: I can’t say for sure. In any case, I see that there are increasingly more qualified candidates—regardless of age or expertise—who are eager to take on a role with responsibility. Our age range spans from 20 to 65, and we have 16 or 17 different nationalities among our staff. And we’re proud to have such a diverse team. 

Where do you stand in Germany in terms of premium? 

Dittmann: For us, Germany is one of the driving countries in Europe, and that is reflected accordingly in the figures. 

So does the largest share of the EUR 500 million come from Germany? 

Dittmann: No, a share corresponding to the size of the German market. 

So half of it? 

Dittmann: No, that would be presumptuous. France, in particular, is also a huge market for us.  

Are you planning further market entries, or are you first building the business where you are already present? 

Brand: We will continue to invest where we already have a presence, such as Germany, France, and Italy. But we still see areas in Continental Europe where we are not yet present or where, as in Belgium and the Netherlands, we are only just beginning. There, the initial investments first have to be made in the form of the management team and underwriting and claims units. And then, looking ahead, there are also the Nordic countries, where we are not yet represented. 

When do you plan to launch there? 

Brand: We’re not planning to do everything at once; instead, we want to get the order right and not take on too much at once. Since we’ve only been active in this European industrial insurance market for three and a half years, I believe it’s particularly important that we focus our expansion plans on where we can create the greatest value for our customers and partners. This builds lasting trust and further strengthens our reputation as a long-term and reliable partner. 

Do you sense any concerns among customers who might fear that, as a foreign player, you might no longer be in the German market in three years? One example is the insurer Everest, which suddenly shut down its operations here following a global decision. 

Dittmann: Given the latest market developments, it’s understandable to question the sustainability of business relationships. We’ve been in Germany for more than 50 years, which is why our starting point differs in key respects from that of many other market participants. Furthermore, we are building an insurance company, not just a market-facing facade. And as Mr. Brand explained, we do not take any steps that we cannot handle. This is clearly evident from the past three years, during which we have built up our non-Japanese business in Germany.  

In what way? 

Dittmann: We could have underwritten a great deal more business here; that would not have been a challenge at all, especially not three years ago, when the market was still relatively tough. However, it has always been our clear strategy to operate sustainably and to underwrite only what we could actually absorb as claims. We promised our clients that we would grow with each renewal over the long term, and we’ve kept that promise. Building this partnership sustainably is exactly what creates trust on the part of both clients and brokers. 

Is it somewhat easier dealing with a Japanese owner than if there were a US company in the background demanding rapid growth?  

Dittmann: I wouldn’t put it that way. Of course, we also have to think in economic terms, but we essentially have the best of both worlds: the patience of the Japanese and the dynamism of the American spirit. That’s a great combination. 

How does Sompo differ from other Japanese players operating in this country? 

Expert insight

I can’t speak for other insurers, but I can tell you what Sompo does. We have a very entrepreneurial culture – a culture of empowerment, accountability, and performance. We want decisions to be made locally and with an entrepreneurial mindset.

That’s a key differentiator in the market. On the one hand, we have our core Japanese values, with which we identify, but at the same time we can think and act entrepreneurially – and do so at the local level.

Ralph Brand

President, Insurance, Continental Europe & Turkey

You launched your operations here during a tough market phase. In which areas has the market noticeably eased, and in which has it not yet done so? Can you give a brief overview of how things currently look here in Germany?  

Dittmann: I don’t think there’s such a thing as a “soft market,” any more than there’s a “hard market.” It always depends heavily on the specific line of business. In the financial lines—particularly in D&O—we came from a very hard market that softened relatively quickly and is now stabilizing, much like the cyber market. There was quite a bit of activity there as well, with many MGAs entering the market, evidently with a great deal of courage. In the traditional lines, transportation insurance is quite stable. The supply of property insurance has broadened again after an extreme shortage, but even there, of course, it depends heavily on the type of business, as always.  

But premiums in the property business are now falling quite significantly, aren’t they? 

Dittmann: The property business faces competition—that’s how I’d put it. But of course, that’s also the momentum we need to grow. 

Are there specific areas where the market is already tightening up again?  

Dittmann: The more international the business is, the more stable the prices are. That’s why our target customer is primarily a multinational corporation.  

In which areas do you operate as a leading insurer, and in which ones do you not yet?  

Dittmann: In D&O, cyber, liability, and transportation, it’s relatively straightforward. As for property insurance, we’re back to what Mr. Brand said: We don’t want to promise anything we can’t deliver. To serve large industrial clients in property insurance, we need a support network, and we’re currently building that. However, we already have clients for whom we are the lead insurer. Could we have 100 more right now? Certainly not at the moment. But tomorrow—that has to be our goal.  

“Tomorrow” is a rather elastic term. 

Brand: One must also keep reminding oneself that we have only been active and investing here for just over three years. That makes it all the more remarkable, in my view, that we have already written more than 100 international programs. Naturally, many of them are smaller, but there are also larger ones involving 40, 50, or 60 policies. That is a good sign for us that we are on the right path. We also benefit from the fact that, unlike other industrial insurers, we have few legacy systems and are able to set up lean processes, making us highly competitive, especially in the service sector.  

Sompo recently acquired Aspen. That gives you Lloyd’s access again. Does the German or Continental European client benefit from that? 

Basically, it provides another way of sourcing capacity. If you look more closely at Aspen, you can see that we had only limited overlap in Continental Europe. The client can decide through which channel they obtain capacity, and if that is London, that is also fine. Lloyd’s gives us additional options in international programs, particularly where we are not yet represented with our own licenses and can now use the new platform. 

Can you imagine making further acquisitions in order to achieve growth targets or to expand in specialty business? 

Brand: We’re pursuing significant growth targets, and a combination of organic and inorganic growth always plays a role in that. In Europe, we’ve initially focused on organic growth. It’s a rather lengthy and also expensive process, it must be said. But it’s worth it because we’re free to make our own strategic decisions about which business areas and geographies we operate in, and we can attract the best talent who share our philosophy and values.  

We see a number of opportunities to further expand our business in Europe, and we’re keeping our options open. If there were an opportunity for inorganic growth in continental Europe, I wouldn’t say we’d be fundamentally uninterested. But my personal focus right now is on further developing our organic growth.  

What comes next in industrial insurance? Will we see further major mergers and acquisitions? 

Expert insight

The trend still exists. The willingness to invest seems to be there, and size in itself still appears attractive in an environment of skilled labor shortages and process-related challenges. The interesting thing about this consolidation is that it repeatedly gives rise to smaller new ventures — MGAs or other vehicles that establish themselves in the market. That is good for the market because it energizes it.

Malte Dittmann

Country Manager, Insurance, Germany & Austria

Brand: I also do not think the consolidation phase we are currently seeing will come to a standstill. From time to time, that can also be an advantage for us, particularly when mergers are not complementary but instead lead companies to have to reduce capacity or to want to do so. That, in turn, allows us to make offers. 

How do you approach managing general agents — do you use MGAs to achieve growth, or are you rather cautious? 

Dittmann: It is important to understand what MGA business means. We are an insurer, so we are more than just a provider of capacity. We invest heavily in claims, operations, and finance. Our profile is different from that of a capacity provider for MGAs. We have to weigh where the MGA is a growth lever and where it is a limiting factor, especially because we see ourselves as a lead insurer. The MGA topic is fundamentally relevant, also because many MGAs are currently emerging. Nevertheless, we remain critical because it is also a cost issue. 

Would a decision like Allianz’s — outsourcing business in an entire segment, in that case cyber, to an MGA — be conceivable for Sompo? 

Brand: I don’t want to comment on our competitors’ activities. In that regard, I can only say that MGAs are of interest to us in the SME sector, where we can work with partners to develop a distribution capability that we couldn’t build on our own. These often involve innovative technological approaches that are certainly valuable to us in the long-term orientation of our partnership with MGAs. I cannot imagine handing over an entire business segment like cyber to an MGA. In the industrial and commercial business, however, I take a rather critical view of the extensive transfer of individual products—such as cyber—to an MGA partner. We take a holistic view of customers in the industrial segment and strive to serve them optimally and from a single source as part of a comprehensive strategy that takes into account all the products and services we offer.  

So you would rather control that yourselves? 

Brand: We are always interested in being in direct contact with the client, of course not to the exclusion of the broker, but in conjunction with the broker. That is a decisive advantage in industrial business because it is a people business. 


First published by Versicherungsmonitor 

About Sompo

We are Sompo, a global provider of commercial and consumer property, casualty, and specialty insurance and reinsurance. Building on the 138 years of innovation of our parent company, Sompo Holdings, Inc., Sompo employs approximately 10,000 people around the world who use their in-depth knowledge and expertise to help simplify and resolve your complex challenges. Because when you choose Sompo, you choose The Ease of Expertise™.

“Sompo” refers to the brand under which Sompo International Holdings Ltd., a Bermuda-based holding company, together with its consolidated subsidiaries, operates its global property and casualty (re)insurance businesses. Sompo International Holdings Ltd. is an indirect wholly-owned subsidiary of Sompo Holdings, Inc., one of the leading property and casualty groups in the world with excellent financial strength as evidenced by ratings of A+ (Superior) from A.M. Best (XV size category) and A+ (Strong) from Standard & Poor’s. Shares of Sompo Holdings, Inc. are listed on the Tokyo Stock Exchange.

To learn more please follow us on LinkedIn